Quantitative research · PhD, UC Santa Barbara

Sam Babichenko

Quantitative researcher at Wells Fargo in Charlotte. I work on game theory, empirical Bayes, machine learning, and quantitative finance, and increasingly on high-dimensional probability and statistics. My PhD work at UCSB solved the problem of forecasting the forecasts of others, which economics has had to work around since Keynes. Here I share projects and writing about what’s been on my mind. Feel free to reach out!

New here? Start with the noise-state, explained, or solve a game in your browser.

the noise-state: what player i believes, at time t, about the shock at u

Interactive Demos

Illustrated Explanations

Projects

Noise-State Calculus for Dynamic Games with Strategic Information

My dissertation. Each player keeps estimates of the primitive shocks instead of belief hierarchies, so beliefs, prices and policies are impulse responses and equilibrium is a fixed point in them. The information wedge prices changing an opponent's beliefs.

researchdissertation

Forecasting and Manipulating the Forecasts of Others

Exact equilibrium characterization of finite-player continuous-time LQG games with endogenous signals

researchgame theory

Decision Mesh

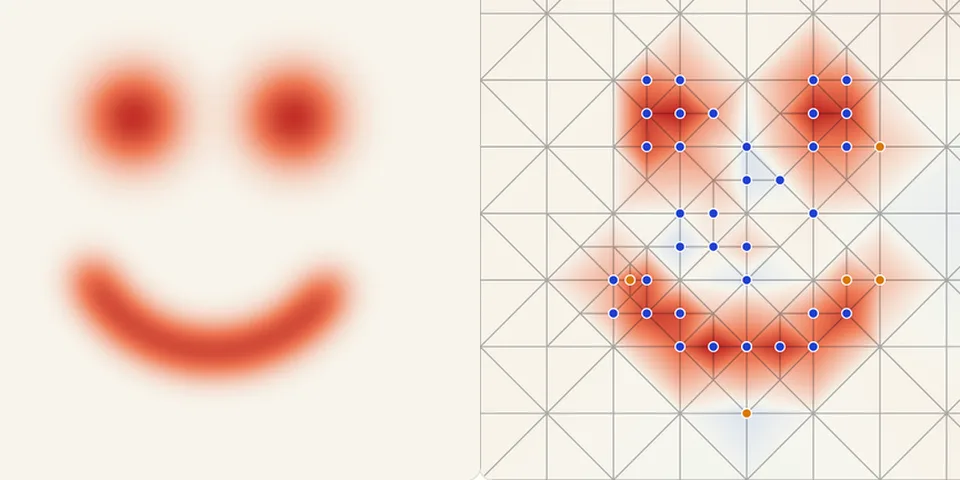
Adaptive, continuous regression that makes grounded, systematic decisions about where to refine the surface, and decomposes the data into the surface, unit-level effects, and pure noise. The rectangular version splits one axis at a time, like a decision tree, so it scales to higher dimensions. It's also very interpretable, so it's easy to tinker with.

Writing

All writing →